How ALTA 50 Man Saves a Monday Closing
By
WWLT
Effective Monday, November 2, 2026
His Powers: What It Covers
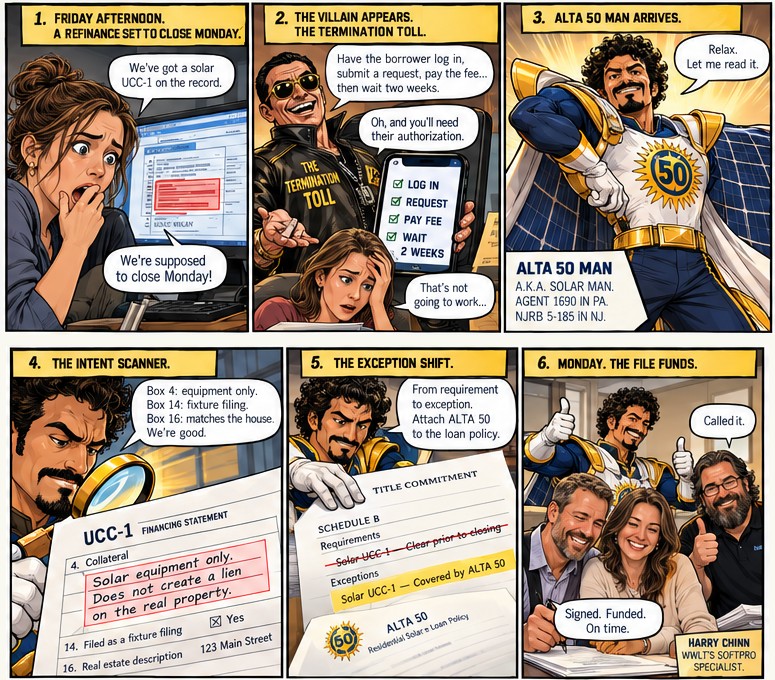
ALTA 50 protects the lender if a court later rules that a recorded solar power purchase agreement, solar panel lease or solar UCC-1 financing statement is an interest in the land or a lien on the title. We no longer wait weeks for the solar company to terminate or subordinate its filing. We review the document, show it as an exception and cover it with the endorsement.
Where He Works: When You Can Use It
- Policy: loan policies only, refinance or purchase loan. Never on an owner’s policy.
- Property: the land must have an existing one-to-four family home.
- Timing: the solar document must already be recorded when the policy is issued.
- Not available: Texas, Florida, New York and Delaware.
- State versions: Pennsylvania issues TIRBOP 1690. New Jersey issues NJRB 5-185, the New Jersey Solar Endorsement.
Calling Him In: How to Underwrite It
- Review the UCC-1: If it passes, move it from Schedule B-I to a Schedule B-II exception. Keep the exception showing, because ALTA 50 covers it.
- Add the endorsement to the loan policy in SoftPro: In AR, IN, KY, MS and NH, pick the row that matches the file’s underwriter: FATIC for First American, FFNA for the Fidelity family, ORT for Old Republic.
- New Jersey only: on the endorsement, enter the solar document’s recording date, its book and page or instrument number, and the B-II exception number.
Send It to Underwriting When
- The UCC-1 doesn’t pass: Box 4 reaches the land or the house, Box 14 isn’t a fixture filing, or Box 16 describes a different property.
- It’s not a UCC-1: the document is a solar lease or power purchase agreement memorandum.
- It’s PACE: a PACE lien or assessment is a lien, not a solar contract, and ALTA 50 does not cover it.
- The property doesn’t qualify: it is commercial, vacant land, or more than four units.
His Kryptonite: What It Doesn’t Do
- It doesn’t make the panels the lender’s collateral.
- It doesn’t cover access to the system, or damage or loss in value from installing, maintaining or removing it.
- It doesn’t cover solar documents recorded after the policy date.